Level 1
Mar 26, 2026 4:55 PM UTC
Solved

Excess 2024 Roth IRA Contribution

My wife and I accidentally contributed $7000 to her Roth IRA account in 2024 directly rather than using the "backdoor roth" method, and her AGI is above the allowed amount for direct Roth IRA contribution. I am now trying to fix the issue. Since it's now 2026 and I've missed the extended filing deadline for 2024, I assume we will have to withdraw the contribution and pay the penalty.


Can someone confirm if these steps are correct?


  1. Withdraw the original amount contribution amount of $7000 (assume I will get a 1099R form next year showing this as an early distribution and have to pay the 10% penalty next year as well)
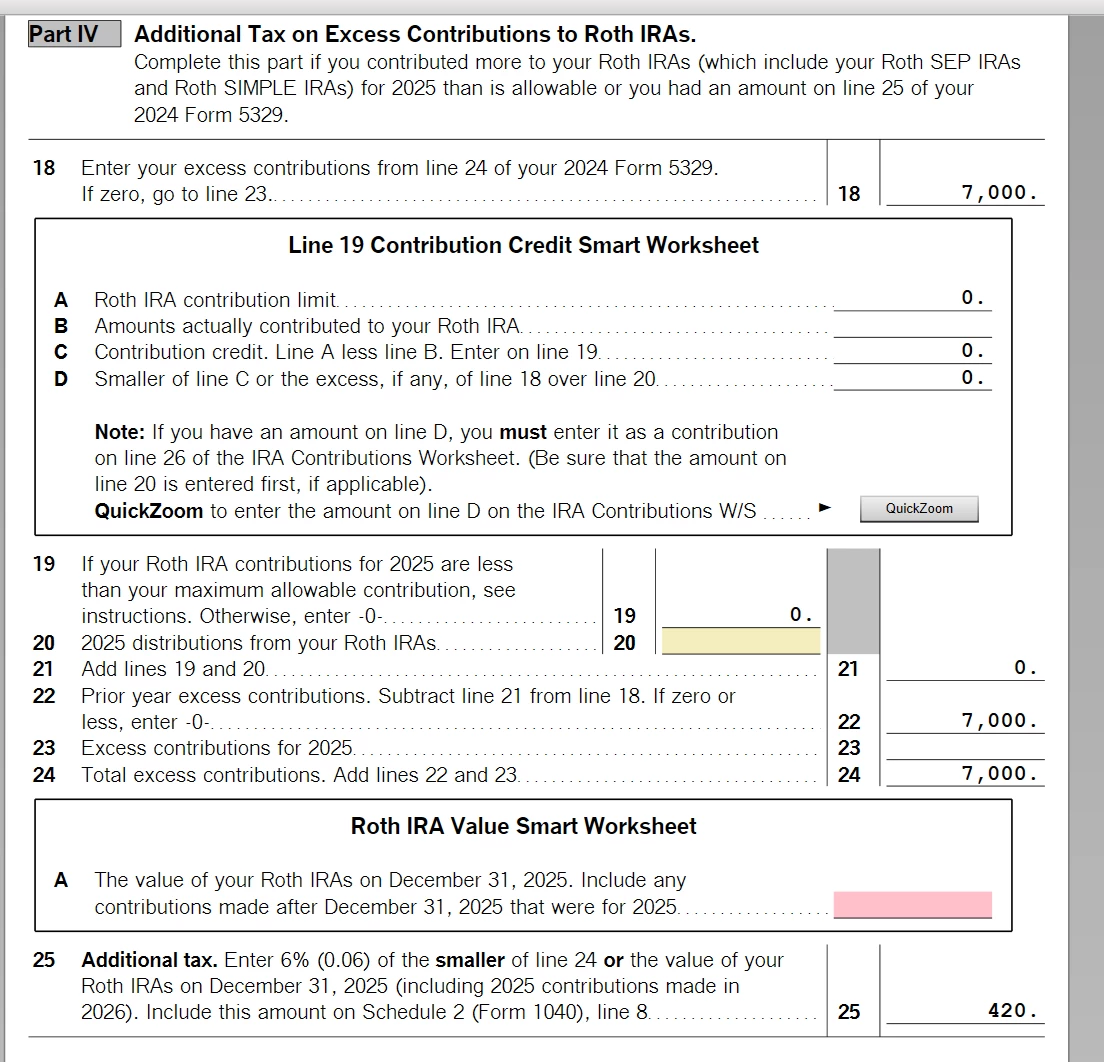
  2. Fill out 5329 form for 6% penalty with my 2025 return. I have done this using Turbotax for the 2025 return, can someone confirm this looks correct: 
     

  3. File 5329 form  for 6% penalty for 2024 amended return. 
  4. Amend 2024 tax return 8606 form? When we filed the 2024 return, we thought we had contributed to a traditional IRA, not Roth IRA, so we filed 8606 for my wife with the $7000 as a nondeductible traditional IRA contribution.

Please let me know if above is correct or if I'm missing anything. Thank you!
    RogerD1
    RogerD1Answer
    Alumni - Intuit
    Mar 26, 2026 9:04 PM UTC

    Yes, you will need to amend your 2024 tax return and switch the non-deductible traditional IRA contribution to an excess Roth contribution.  And, yes it will be subject to the 6% penalty, which is $420 on the $7,000 contribution.  This will also amend the Form 8606 for 2024 to show that it was not a non-deductible traditional IRA contribution.


    Because you missed the filing deadline to make a corrective distribution for the 2024 contribution, and the funds were still in the account for all of 2025, you will also pay the 6% penalty for 2025 - the screenshot of the form 5329 that you sent is correct.


    To avoid getting the 6% penalty for 2026, you can withdraw the original contribution of $7,000.  You won't have a 10% penalty on the distribution because of IRS ordering rules for Roth IRAs:  Contributions are the first funds to be withdrawn from the IRA and they are always free of taxes and penalties.  You'll get the 1099-R for that early in 2027 to report on your 2026 tax return.

    **Say "Thanks" by clicking the thumb icon in a post. **Mark the post that answers your question by clicking on "Mark as Best Answer"

    1 reply

    RogerD1
    RogerD1Answer
    Alumni - Intuit
    Mar 26, 2026 9:04 PM UTC

    Yes, you will need to amend your 2024 tax return and switch the non-deductible traditional IRA contribution to an excess Roth contribution.  And, yes it will be subject to the 6% penalty, which is $420 on the $7,000 contribution.  This will also amend the Form 8606 for 2024 to show that it was not a non-deductible traditional IRA contribution.


    Because you missed the filing deadline to make a corrective distribution for the 2024 contribution, and the funds were still in the account for all of 2025, you will also pay the 6% penalty for 2025 - the screenshot of the form 5329 that you sent is correct.


    To avoid getting the 6% penalty for 2026, you can withdraw the original contribution of $7,000.  You won't have a 10% penalty on the distribution because of IRS ordering rules for Roth IRAs:  Contributions are the first funds to be withdrawn from the IRA and they are always free of taxes and penalties.  You'll get the 1099-R for that early in 2027 to report on your 2026 tax return.

    **Say "Thanks" by clicking the thumb icon in a post. **Mark the post that answers your question by clicking on "Mark as Best Answer"